Use the current cashier as the method list
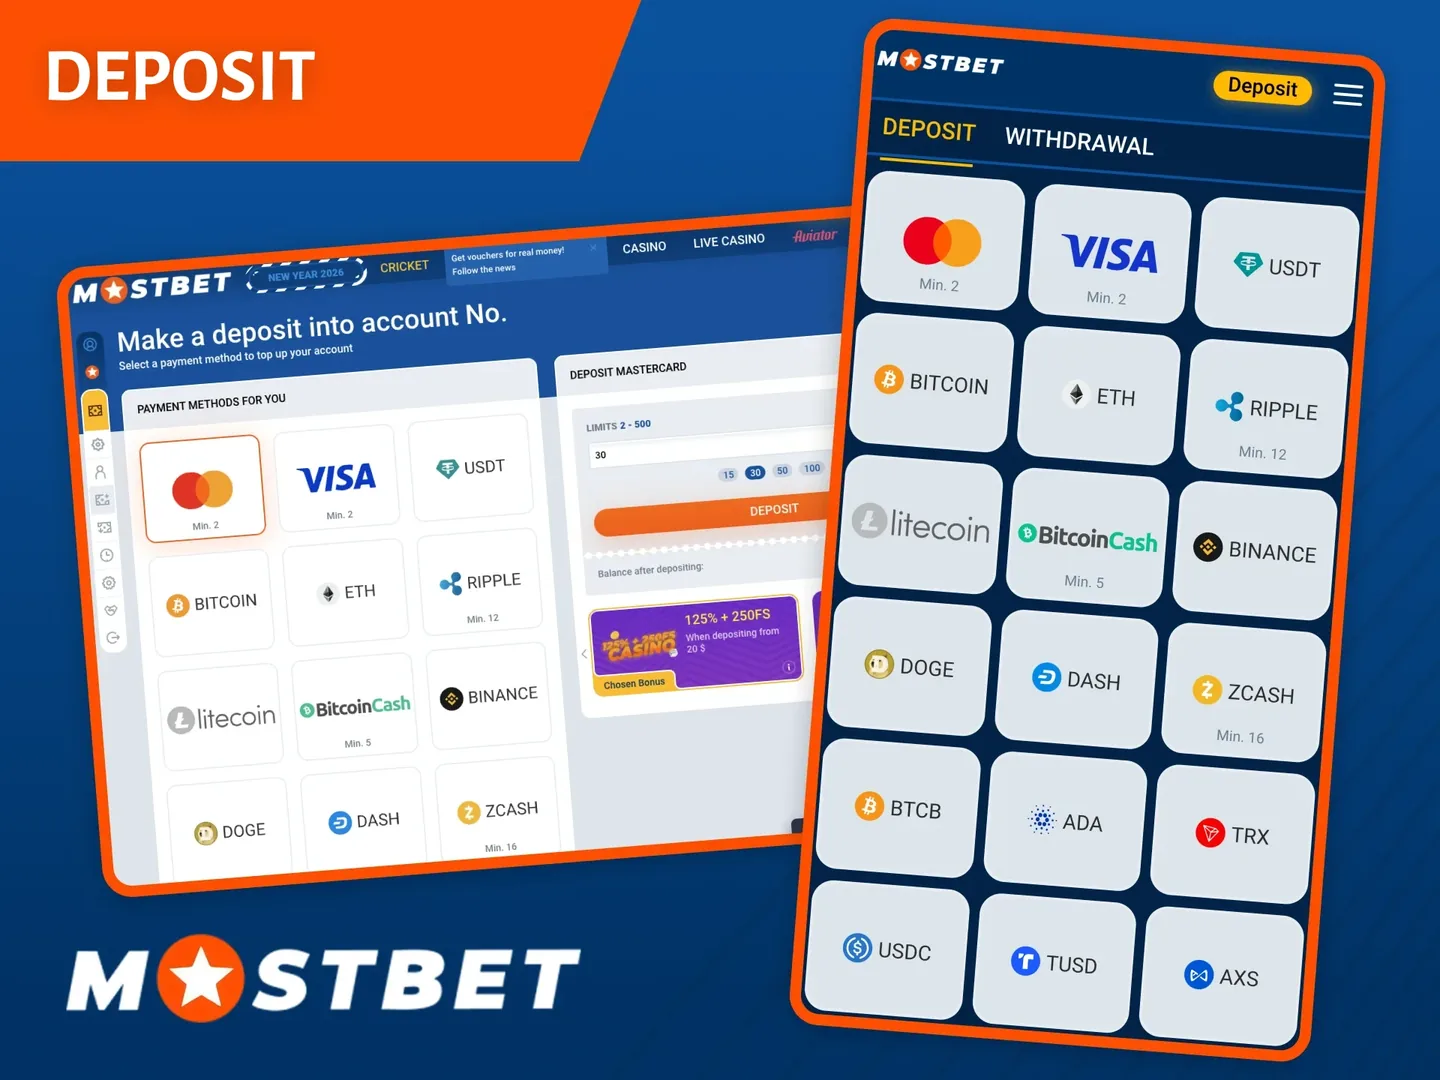
Payment availability depends on location, currency, account status and the provider’s current service. A card, wallet or UPI logo in an illustration does not establish availability for your account. Open the cashier after logging in and inspect the methods actually offered.
Use a payment account in your own name and check any verification requirements before transferring. Third-party payments can make ownership checks and refunds more difficult. If a method is absent, do not send funds to details copied from a screenshot, social message or previous transaction.
| Method category, if available | Check before confirming | Record to keep |
|---|---|---|
| Card | Currency, authentication and issuer charges | Payment reference and masked card identifier |
| Bank or local transfer | Current recipient details and required reference | Bank transaction ID |
| E-wallet | Account ownership and wallet currency | Wallet receipt |
| Digital asset | Asset, network, address and minimum | Transaction hash |
Deposit in a traceable sequence
- Sign in and confirm the account ID and currency.
- Open deposit and choose an available method.
- Read the displayed minimum, maximum and any fee or conversion information.
- Enter an amount within your personal budget and review any bonus selection separately.
- Check the final recipient or authorization screen before confirming.
- Complete the payment-provider authentication without sharing codes.
- Save the reference and check the account’s transaction history.
Submit the payment once. A slow screen does not establish failure, and a second submission can create a second transaction. If the confirmation is unclear, compare the operator history and provider statement before trying again.
Minimums, fees and conversion: separate the numbers
The minimum amount is a cashier rule, not a recommendation to spend. A promotion may require more than the payment method’s minimum, while a free-spin threshold may differ again. Read each condition separately instead of assuming one qualifying amount covers everything.
For a clearly labelled example, suppose the cashier requests 1,000 account-currency units and the payment provider adds a 2% fee. The total debit would be 1,020 units if there is no further conversion. This is arithmetic, not a statement that the operator or your provider charges that fee.
What arrives can differ from what leaves
A cross-currency payment can involve a provider’s exchange rate and a separate conversion charge. Compare the final debit currency with the account currency. If the confirmation shows an unexpected amount, cancel before authorizing and ask the provider to explain it.
Decide on a promotion before the first payment
A first-deposit promotion may depend on activation, timing, payment method and account eligibility. Read its terms before paying. A bonus balance is not necessarily withdrawable cash, and using it can introduce wagering or game restrictions.
The bonus guide explains percentage matches and turnover. As an illustration, a 125% match on a 1,000-unit qualifying deposit would calculate to 1,250 bonus units before applying a cap. If the real terms exclude the payment method, that arithmetic does not create entitlement to a bonus.
Save the applicable terms and confirmation if you accept an offer. Do not make additional deposits solely to repair an unclear promotion status. Ask support to check the first transaction and activation history.
Pending, failed and debited-but-missing transactions
| What you see | What it means | Useful next action |
|---|---|---|
| Pending | The process has not reached a final recorded outcome | Check the stated processing guidance |
| Failed, no provider debit | The payment may not have completed | Confirm both histories before retrying |
| Provider debited, balance unchanged | The transfer and account credit need reconciliation | Send the reference to verified support |
| Reversed or refunded | Funds may be returning through the original route | Track the provider’s reversal status |
Do not assume that “pending” always lasts a fixed number of minutes. Method-specific checks, bank processing and account reviews affect the sequence. Record the time and timezone so support can match the events accurately.
What to include in a missing-payment request
Give support your account identifier, payment time, amount, currency, selected method and transaction reference. Attach a receipt with unrelated transactions and sensitive details hidden. Never include a password, OTP or full card security code.
Ask whether the payment was received, whether it was allocated to the correct account and whether any action remains. Keep the case reference. If the operator and payment provider show different statuses, ask each to explain its own stage rather than describing the entire transfer as “lost.”
For digital assets, the network and address matter as well as the amount. A transaction hash can establish a network transfer but not automatically prove that an operator credited the correct account. Wrong-network transfers may not be recoverable; verify the exact instructions before sending.
Think about the exit route too
Before making a deposit, inspect the withdrawal process. Deposit support does not guarantee that the same method can receive payouts, and identity checks may still be required. Read the relevant rules while you can make an informed decision.
Set a fixed spending limit that does not depend on winning. Do not use repeated payments to chase a loss or solve a delayed payout. If controlling spending becomes difficult, pause and use the available account-limit or exclusion tools.
Payment logos identify methods discussed in this guide; they do not confirm availability for your account or location.

Questions answered
Are all advertised payment methods available to every account?
No. Use the methods currently displayed in the authenticated cashier for your account and location.
What if my bank shows a debit but the balance is unchanged?
Check both transaction histories and contact verified support with the payment reference before submitting another transfer.
Is the minimum deposit also the bonus minimum?
Not necessarily. Payment limits and promotion thresholds can be different.
Can I use someone else’s payment account?
Use your own payment account and follow the operator’s ownership rules. Third-party payments can complicate verification and refunds.
Published by mostbettcasinos.com. Read our review methodology and editorial responsibilities. For corrections, contact the publisher.